Fintech Credit Cards in India
As Indian consumers have adapted to digital payments, especially UPI, Fintech startups in the country have come up with a variety of lending products, including instant personal loans and BNPL (Buy Now Pay Later) services like Amazon Pay Later, LazyPay, and many more. Some Fintechs have taken the BNPL model to a different level by offering physical payment cards against a line of credit that works very much like credit cards for almost all practical purposes. As most of these companies are not registered NBFCs, these BNPL cards are issued in collaboration with a financial partner, such as a bank or NBFC. Just like credit cards, BNPL cards are also issued on payment networks like Visa/MasterCard and can be used at any retail store (online or offline). Moreover, you can even earn reward points/cashback on these BNPL cards.
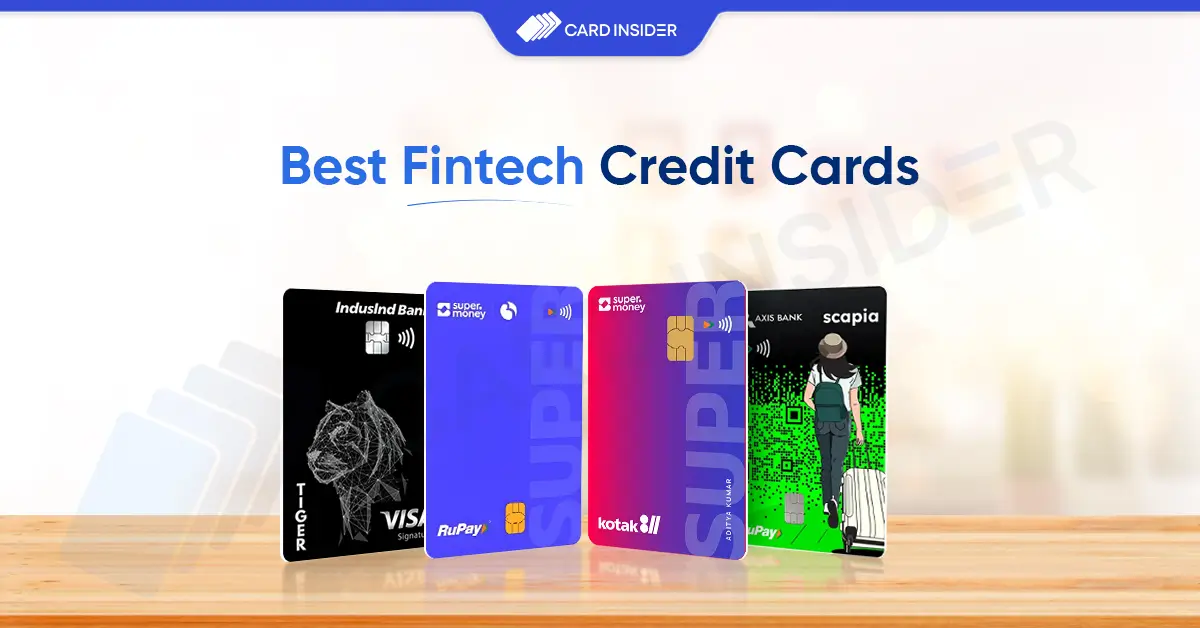
While some startups have launched BNPL cards, others have come up with a traditional credit card in collaboration with a bank/NBFC. Such credit cards include One Card and Scapia Credit Card. In this article, we will discuss the features and benefits of the most popular fintech cards and also learn the critical differences between traditional credit cards and these new-age cards.
On This Page — Jump to a Card
- Scapia Axis Bank Credit Card
- IndusInd Bank Tiger Credit Card
- Scapia Credit Card
- Axis Bank SuperMoney RuPay Credit Card
- Kotak811 Super Money Credit Card
- Utkarsh Small Finance Bank superCard Credit Card
- Zagg Credit Card
- BOBCARD Uni GoldX Credit Card
- YES Bank POP CLUB Credit Card
- OneCard Metal Credit Card
- SBM ZET Credit Card
- slice UPI Credit Card
- Edge CSB Bank RuPay Credit Card
- Unity Bank BharatPe RuPay Credit Card
- CUB SalarySe Level Up Credit Card
List of Fintech Credit Cards in India 2026
Though there is not a very long list of fintech credit cards available in the Indian market as of now, not everyone is aware of all these cards and their features. Having similar features to credit cards, these cards work on the concept of Buy Now Pay Later. In this article, you can find the list of the best Fintech Credit Cards in India, along with their detailed features and all other necessary information:
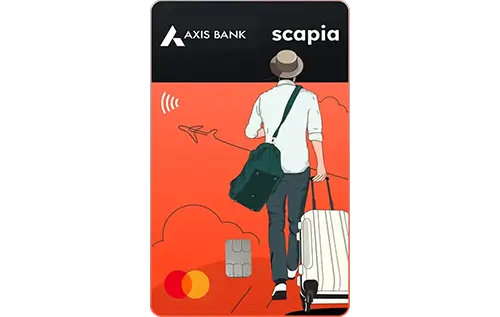
- Joining Fee
- Lifetime Free
- Annual Fee
- Lifetime Free
- Best Suited For
- Travel | International Spends
- Rewards Type
- Reward Points
Rewards rate and welcome benefits
Rewards Rate1% Value Back on Eligible Spends of ₹500+ on RuPay, 2% Value Back on Eligible Spends of ₹20+ on Mastercard, and 4% Value Back on Flights, Hotels & Bus Bookings via Scapia App
Welcome BenefitsN/A

- Joining Fee
- Nil
- Annual Fee
- Nil
- Best Suited For
- Movies | Travel
- Rewards Type
- Reward Points
Rewards rate and welcome benefits
Rewards RateUpto 6 Accelerated Reward Points on Every ₹100 Spent on Eligible Transactions
Welcome BenefitsN/A

- Joining Fee
- Lifetime Free
- Annual Fee
- Lifetime Free
- Best Suited For
- Travel | Shopping
- Rewards Type
- Reward Points
Rewards rate and welcome benefits
Rewards Rate20% Scapia Coins on Travel Bookings (~4%) & 10% Scapia Coins on All Other Transactions (~2%)
Welcome BenefitsN/A

- Joining Fee
- Lifetime Free
- Annual Fee
- Lifetime Free
- Best Suited For
- UPI
- Rewards Type
- Cashback
Rewards rate and welcome benefits
Rewards Rate3% Cashback for UPI Spends Via super.money UPI and 1% Cashback on All Other Qualifying Spends
Welcome BenefitsN/A

- Joining Fee
- Lifetime Free
- Annual Fee
- Lifetime Free
- Best Suited For
- Shopping
- Rewards Type
- Cashback
Rewards rate and welcome benefits
Rewards Rate1% Cashback On UPI Transactions Via Super.Money App
Welcome BenefitsN/A

- Joining Fee
- Lifetime Free
- Annual Fee
- Lifetime Free
- Best Suited For
- UPI
- Rewards Type
- Cashback
Rewards rate and welcome benefits
Rewards Rate5% Cashback at Myntra, 3% Cashback on Cleartrip, and 2% Cashback on Flipkart. 1% Cashback on All UPI and Non-UPI Transactions
Welcome BenefitsNone

- Joining Fee
- N/A
- Annual Fee
- N/A
- Best Suited For
- UPI
- Rewards Type
- Reward Points
Rewards rate and welcome benefits
Rewards Rate3% Zagg Coins on Zagg UPI Spends
Welcome BenefitsN/A

- Joining Fee
- Nil
- Annual Fee
- Nil
- Best Suited For
- Shopping
- Rewards Type
- Reward Points
Rewards rate and welcome benefits
Rewards Rate1 Uni Coin for Every ₹1 Spent
Welcome BenefitsN/A

- Joining Fee
- LIFETIME FREE (Till 31st March 2027)
- Annual Fee
- LIFETIME FREE (Till 31st March 2027)
- Best Suited For
- Shopping | UPI
- Rewards Type
- Reward Points
Rewards rate and welcome benefits
Rewards Rate10 POPcoins/₹100 Spent Online and 2 POPcoins on Offline Purchases. Instant 5% POPcoins via POPUPI
Welcome BenefitsBenefits Worth ₹5,000 Including 500 POPcoins, Cleartrip Voucher Worth ₹750, Cult Sport Voucher Worth ₹500, Zomato Gold Membership (3 Months) and More

- Joining Fee
- Lifetime Free
- Annual Fee
- Lifetime Free
- Best Suited For
- Shopping | Food
- Rewards Type
- Reward Points
Rewards rate and welcome benefits
Rewards Rate1 Reward Point per Rs. 50 spent, 5x Reward Points on top two spend categories of the month
Welcome BenefitsN/A

- Joining Fee
- Lifetime Free
- Annual Fee
- Lifetime Free
- Best Suited For
- Dining | Shopping
- Rewards Type
- Zet Coins
Rewards rate and welcome benefits
Rewards RateUpto 15% Rewards on Voucher Transactions on ZET App. Flat 2% Rewards on UPI Transactions on ZET App (Coming Soon)
Welcome BenefitsN/A
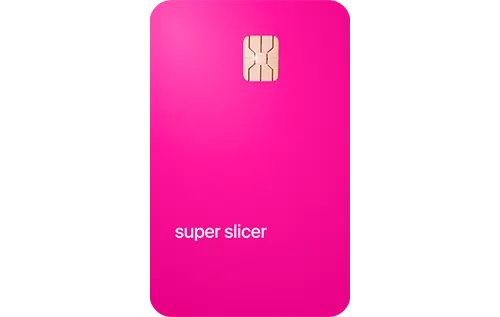
- Joining Fee
- N/A
- Annual Fee
- N/A
- Best Suited For
- UPI
- Rewards Type
- Cashback
Rewards rate and welcome benefits
Rewards RateUp to 3% Cashback on Every Spend
Welcome BenefitsN/A
- Joining Fee
- Nil
- Annual Fee
- Nil
- Best Suited For
- Travel | Dining | Shopping
- Rewards Type
- Cashback
Rewards rate and welcome benefits
Rewards RateEarn Up to 50% Jewels on Eligible Spends
Welcome Benefits₹250 Voucher from Top Brands

- Joining Fee
- LIFETIME FREE
- Annual Fee
- LIFETIME FREE
- Best Suited For
- Shopping
- Rewards Type
- Reward Points
Rewards rate and welcome benefits
Rewards RateUp to 2% Cashback as Zillion Coins
Welcome BenefitsN/A

- Joining Fee
- ₹500 + GST
- Annual Fee
- ₹500 + GST
- Best Suited For
- Shopping
- Rewards Type
- Reward Points
Rewards rate and welcome benefits
Rewards Rate25 Reward Points/₹100 on Transactions made via SalarySe UPI; 1 Reward Point/₹100 on Transactions Made on Other UPI Apps; 5 Reward Points /₹100 on Monthly Spend of Below ₹20,000 and 10 Reward Points/₹100 When Current Bill Exceeds ₹20,000
Welcome BenefitsN/A
Review and Details of Popular Fintech Cards
Many fintech firms have come up with their own BNPL Cards and even traditional credit cards in partnership with their banking partners, which can be either a traditional bank or an NBFC. Here, we have covered the critical highlights of three of the most popular fintech cards listed above.
Scapia Federal Credit Card
Scapia is one of the most popular Fintech credit cards in India. This card is co-branded by Federal Bank and offers some of the most lucrative benefits on travel bookings. Not only is this card offered as lifetime free, but there are zero forex fees associated with it. Customers can easily use this card at merchants across the globe (200 countries). Here is a quick look at some of the features of the Scapia Federal Credit Card.
- 48 days of no interest period. 3.49% monthly interest is charged after the zero-interest period ends.
- 10% Scapia coins on all offline and online purchases.
- Accelerated 20% Scapia coins on all travel bookings (airlines/hotels) made on the Scapia app.
- 5 Scapia coins = ₹1.
- Unlimited free domestic lounge access is provided.
Axis Bank SuperMoney RuPay Credit Card
The Axis Bank SuperMoney RuPay Credit Card is a lifetime free card designed for everyday users who rely heavily on UPI. It offers an impressive 3% cashback on QR payments made via the super.money app and 1% cashback on other spends, capped at ₹500 per billing cycle (₹6,000 annually). With no joining or renewal fee, a fuel surcharge waiver, and seamless cashback credited directly to the statement, it’s a simple yet rewarding card for those who spend around ₹16,500 monthly through UPI.
This card is perfect for maximizing digital spending without worrying about annual charges.
IndusInd Tiger Credit Card
The IndusInd Bank Tiger Credit Card is a lifetime free card that offers good value for individuals who enjoy shopping, movies, and travel. You can earn up to 6 reward points for every ₹100 spent, based on your yearly spend, and the points can be redeemed for cash or KrisFlyer miles. The card also gives 8 free domestic lounge visits, 2 international lounge visits, 4 free golf games or lessons a year, and complimentary movie tickets on BookMyShow. Additionally, it features a low 1.5% forex markup for international transactions and provides air accident insurance coverage.
The primary advantages of this card lie in its lifestyle benefits rather than its reward rate.
OneCard
One Card is a traditional credit card launched by FPL Technologies. Even though this is a traditional credit card, you can easily split your spends into convenient EMIs. Some of the key features of the One Card Credit Card are as follows-
- Lifetime free credit cards are issued in partnership with banking partners, including CSB Bank, Federal Bank, Indian Bank, BOB Financial, SBM Bank, and South Indian Bank.
- You get 1 Reward Point per ₹50 spent with One Card and 5x Reward Points on the top two spend categories of the month. One Reward Point is equivalent to ₹0.10 in monetary terms.
- You are charged a lower mark-up fee of just 1% on making foreign currency transactions with the card.
- In the event of a default on a bill payment, the applicable interest rate is 3.49%.
Utkarsh Small Finance Bank superCard Credit Card
The Utkarsh Small Finance Bank superCard Credit Card is a lifetime free secured card launched with super.money (a Flipkart company), designed mainly for beginners or those looking to build credit. By creating a small fixed deposit starting from just ₹100, users get a virtual RuPay credit card that works on UPI and offers high cashback on several platforms – 5% on Myntra, 3% on Cleartrip, 2% on Flipkart, and 1% on all other spends. Cashback is simple to redeem through the super.money app and can be credited directly to your bank account.
While there are no travel or lounge perks, the card stands out for its low entry barrier, easy approval, and guaranteed returns through FD interest plus cashback, making it a smart choice as a starter or backup card.
How to Choose the Right Fintech Card?
- When choosing a Fintech Card, the very first thing to check is the reward rate. If you spend a lot, then going with a card that offers a higher reward rate or instant cashback would be a wise choice.
- The next important thing to check in a Fintech card is the interest charges applicable to the due amount. It is advisable to settle the bills on time, but in case you default on a payment, then you would face heavy charges on the due amount. Therefore, go with a card that carries lower finance charges.
- Also, look for other benefits provided with the card and compare them with other card features. If you are getting the proper benefits from the right card, then go for the same.
Why Fintech Cards Are Gaining Popularity?
Fintech Cards have changed the credit card industry by bringing new and innovative technologies into the world of payment options. These cards are becoming the 1st payment choice for the following reasons:
- Quick Onboarding: The application process for Fintech Cards is far better and quicker compared to traditional credit cards. Moreover, these cards require very few documents, and sometimes, they don’t even check the credit scores of applicants.
- Great Rewards: The Fintech Cards offer cashback or points on every transaction you make. Moreover, some cards provide great rewards and offers on famous partner merchants that bring you great deals.
- Building Credit Score: Fintech Cards are the best way to build a good credit score or to start the credit card journey. Even if you have a low credit score, you can make it better with these Fintech cards.
Difference Between Credit Cards and BNPL Cards
Both credit cards and BNPL cards are financial tools that allow you to make purchases against a line of credit granted to you by the issuer. However, there are two critical differences between BNPL cards and credit cards: A BNPL card is technically issued against a line of credit granted to you as a personal loan by the issuer. A credit card, on the other hand, is a separate category of financial product in itself. Another difference between a BNPL Card and a credit card is that a BNPL Card allows you to pay off your billed amount in interest-free installments, which is not the case with traditional credit cards. The following table summarises the key differences between a credit card and a BNPL Card-
| Credit Cards | BNPL Cards |
| A separate category of financial product as per RBI norms. | Essentially, it is a line of credit granted against a personal loan- very similar to products like Paytm Postpaid, Ola Money Postpaid, and Amazon Pay Later. |
| You have to pay the entire billed amount by the payment due date (usually 15 to 20 days after the end of the payment cycle). Otherwise, interest is payable on the due amount. | BNPL cards allow you to split your bill into interest-free EMIs to be paid over the next few months. |
| Usually, they offer a higher reward rate. | The reward rate is lower than traditional credit cards in most cases. |
| Allow cash withdrawals from ATMs. | Cash withdrawals from ATMs are not allowed. |
| It can be used for making international transactions. | It cannot be used for making international transactions. |
| Usually have comparatively stricter eligibility criteria (except secured credit cards that are issued against a fixed deposit). | More relaxed eligibility criteria- sometimes. |
Bottom Line
Fintech Cards are far different from regular credit cards, as these are not issued by commercial banks. Moreover, the Fintech cards are just Buy Now Pay Later cards, and they do not even require a high credit score. These cards operate in very easy and straightforward terms. The onboarding process for the Fintech cards is also quick and easy. The Fintech cards are issued with a fixed credit line based on your profile and offer you discounts on merchants and rewards for transactions done with them.
Fintech cards like OneCard, Scapia, and super.money are suitable for students or new to credit young professionals who need a line of credit for their monthly expenses but are not eligible for a traditional credit card. Otherwise, if you qualify for even an entry-level credit card, it is a better idea to go for a conventional credit card, as traditional credit cards not only offer a higher reward rate but also allow you to withdraw cash from ATMs.
A reason to opt for a BNPL card is that BNPL cards will enable you to split your bill into interest-free installments that you can pay over the next few months. If you are someone who likes to make purchases on EMIs, the Buy Now Pay Later model might suit you.
That being said, for most of us, a traditional credit card is, any day, a better pick.
Frequently Asked Questions
Are BNPL cards credit cards?
No BNPL (Buy Now Pay Later) Cards are not credit cards. These cards grant you a line of credit against a personal loan, which you can use for making purchases at online/offline stores.
Is One Card also a BNPL or Pay Later Card?
No, OneCard is a traditional credit card. FPL Technologies Pvt. Ltd. issues OneCard Credit Card in collaboration with its banking partners, such as Federal Bank, Indian Bank, BOB Financial, SBM Bank, and South Indian Bank.
Reader Comments
No comments yet — be the first to share your thoughts.